
Every founder raising from venture capitalists has heard the same names — Sequoia, Andreessen Horowitz, Benchmark — and every limited partner has a mental shortlist of VC firms that supposedly matter. And while these names are well-known, there has, surprisingly, never been a transparent, fully data-driven ranking of which VC firms are actually best at what they do.
Together with Blake Jackson, I built one. Today we release the inaugural 2026 Venture Ranking of the top 100 US-based VC firms, drawn from more than 230,000 investments by nearly 13,000 venture capitalists over a 30-year window.
The full methodology is described in our working paper (Strebulaev and Jackson, 2026). This article covers VC firms; the companion ranking of Top 100 individual VC investors is a separate release.
Get every ranking the moment it drops.
The individual VC ranking and industry breakdowns publish on Substack first. Our main rankings are free to everyone. Paid and founding members get early access, additional rankings, plus extra detail on firms and individuals. An extended version of this ranking (101–200) is now available to paid subscribers.
Why rank firms?
By our estimates, about 5% of venture capitalists have generated roughly 90% of the industry’s profits. The central question in venture therefore — for founders choosing investors, for LPs allocating capital, and for the broader economy that depends on good capital allocation — is identifying who sits in that 5%.
So we set out to build a ranking that is transparent, replicable, and free of editorial judgment. In our methodology, every point traces back to a specific investment in a specific company on a specific date.
What the score measures
Our algorithm rests on six economically grounded factors.
Valuation. Two companies can both be “worth $100 billion” — one as a public market capitalization, the other as a private post-money valuation. These are not the same number. Private post-money valuations systematically overstate true value, because the preferred stock VCs buy carries downside protections that common stock lacks. We discount private valuations uniformly. My work with Will Gornall put the average overstatement for unicorns near 50%.
Dilution. A 10% stake at the first round is not a 10% stake at exit. Two companies can both sell for $1 billion, but if one raised four rounds along the way, its early investors were diluted round after round. We track each investment’s ownership down through every subsequent round.
Net profit. Net profit is more informative than gross profit when investors deploy very different amounts of capital. Turning $10 million into $2 billion is a different achievement from turning $1 billion into the same $2 billion. We subtract the cost of every investment, which rewards capital efficiency and penalizes spraying large checks to produce a few headline wins. In our data, roughly three-quarters of investments returned negative net profits.
Value add. Investors who lead rounds and take board seats contribute more than passive check-writers. We award additional points for these roles, reflecting involvement in a company’s outcome.
Human-capital decay. A VC’s skill, network, and judgment depreciate if not continuously exercised. We discount each investment by the time elapsed since it was made, using a half-life of three years. A dollar of value created in 2022 is worth about fifty cents in 2025 and a quarter if it was created in 2019. Two investors who each turned a 20% stake into a $10 billion IPO can look identical on paper — yet if one invested in 2005 and the other in 2020, the second earned an IRR of 141.9% against 28.7%, and rests on human capital six years old rather than twenty-one. This is what keeps the ranking current: it rewards investors who are good now, not those resting on a single brilliant bet from two decades ago.
Credit between firm and individual. In principle, the points given to each firm are equal to the sum of the points awarded to its partners. However, investors move between firms. When a partner who made their best deals at one firm decamps to another, both firms deserve some credit. We split it — a quarter to the firm where the investment was made, three-quarters to the firm where the partner works now — reflecting academic evidence that most return variation traces to individuals rather than institutions. This is also part of why a firm’s score and its partners’ individual scores can diverge sharply.
The 2026 Top 100 VC firm results
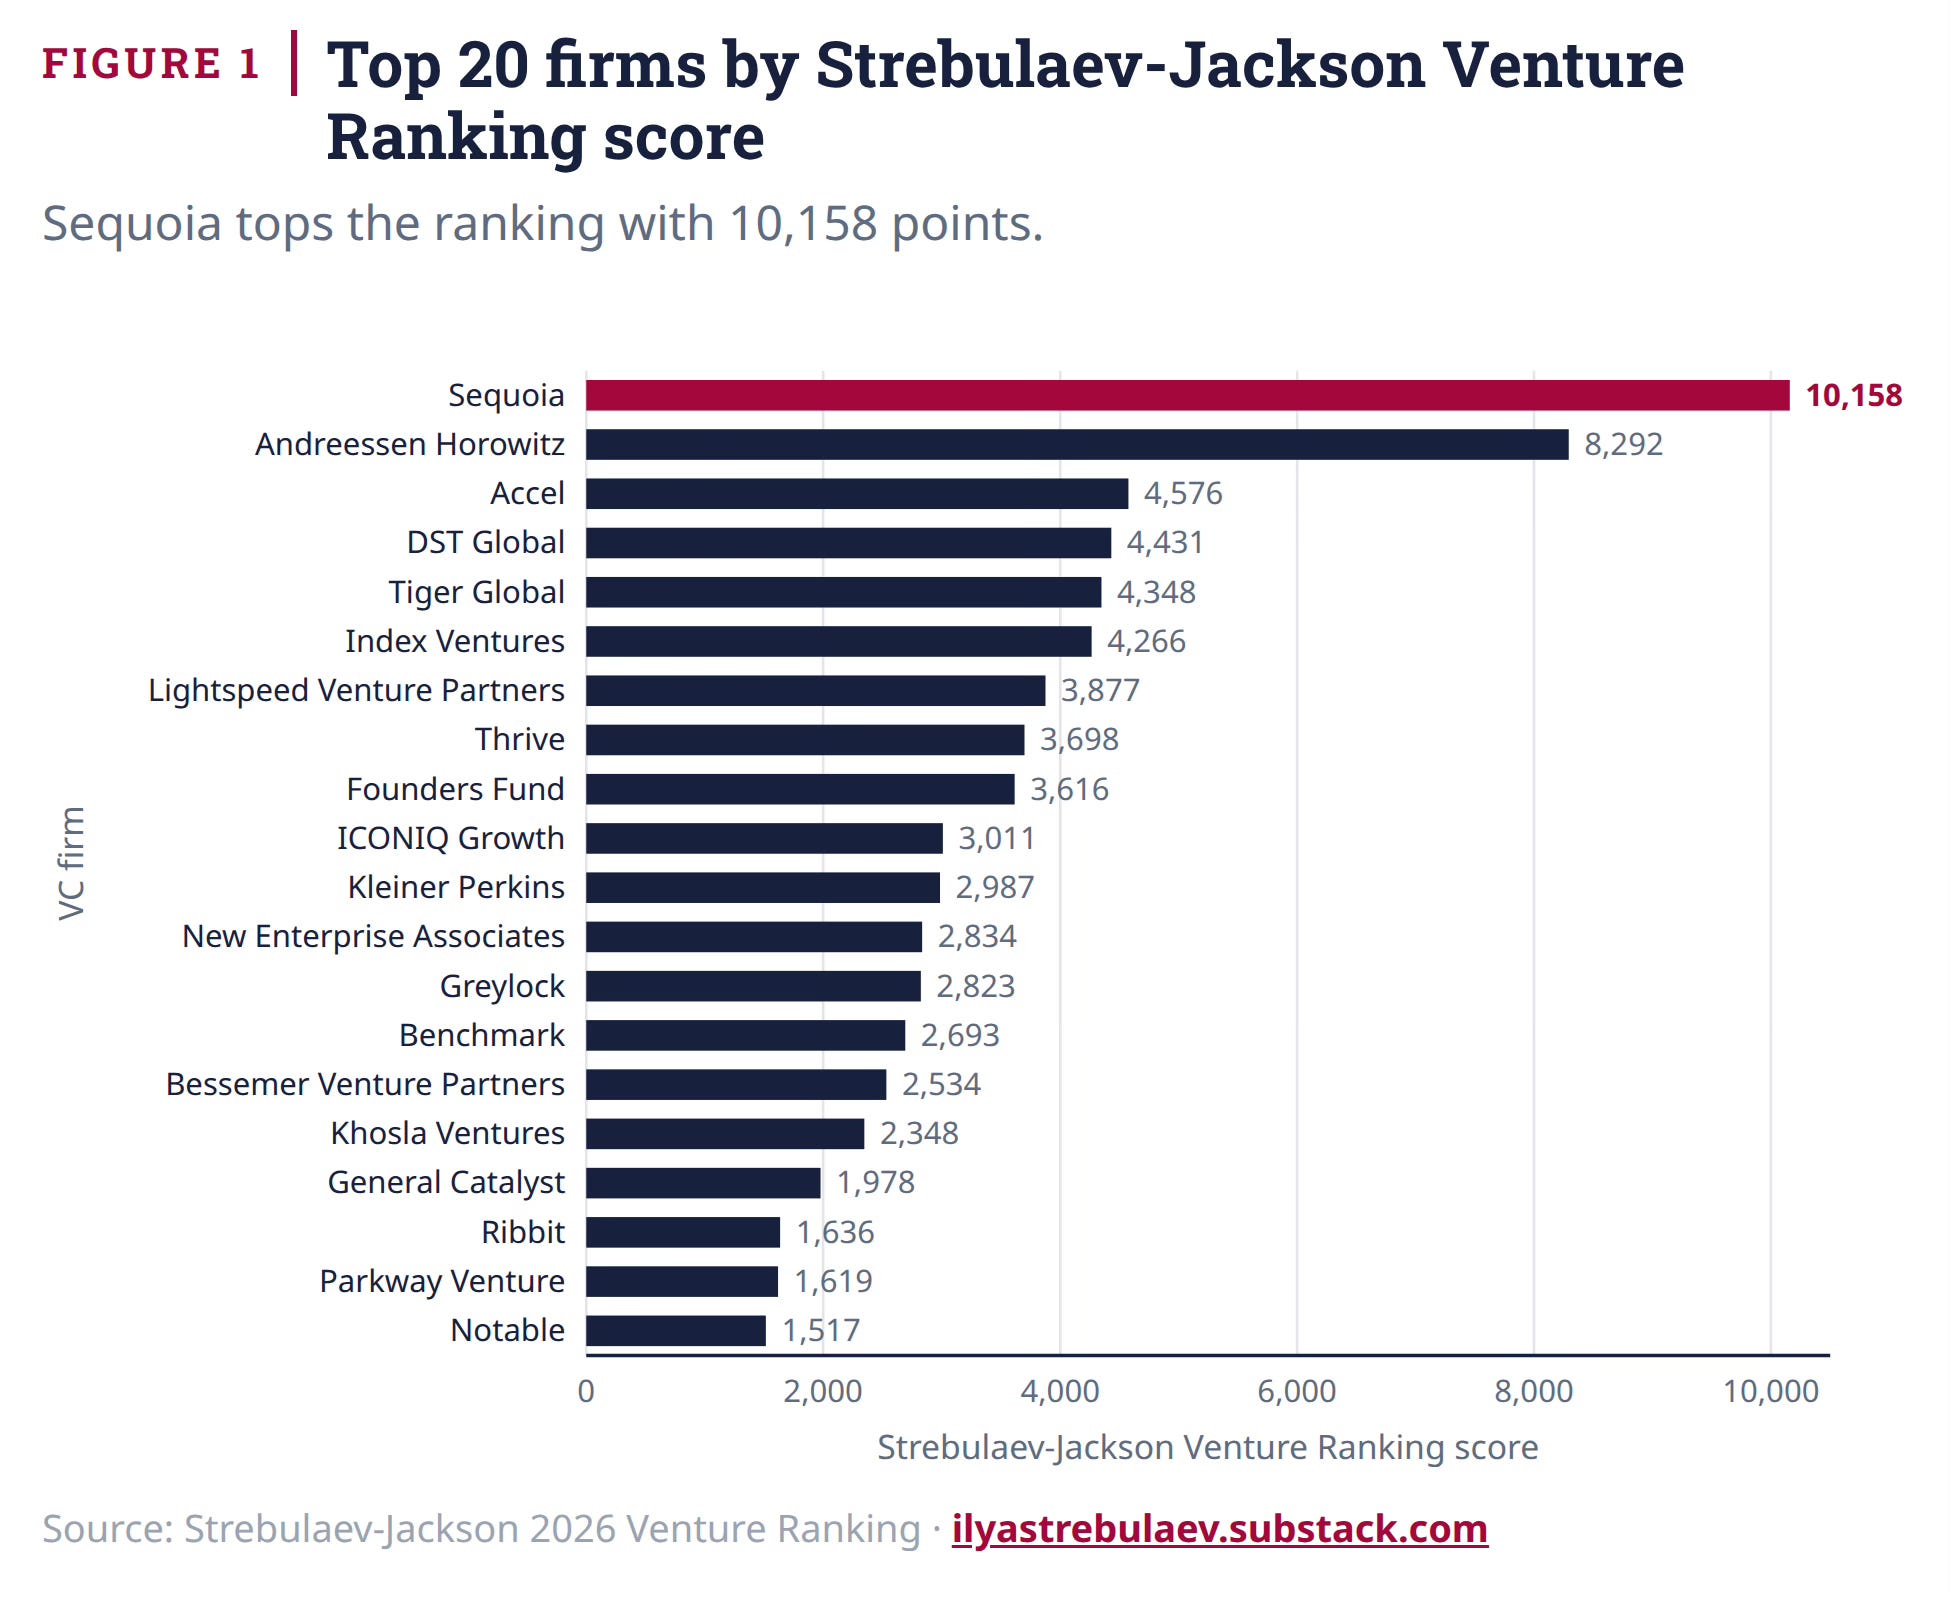
Sequoia tops the ranking with 10,158 points. Andreessen Horowitz is second with 8,292 points. Accel, DST Global, and Tiger Global round out the top five. The top 20 is shown below.
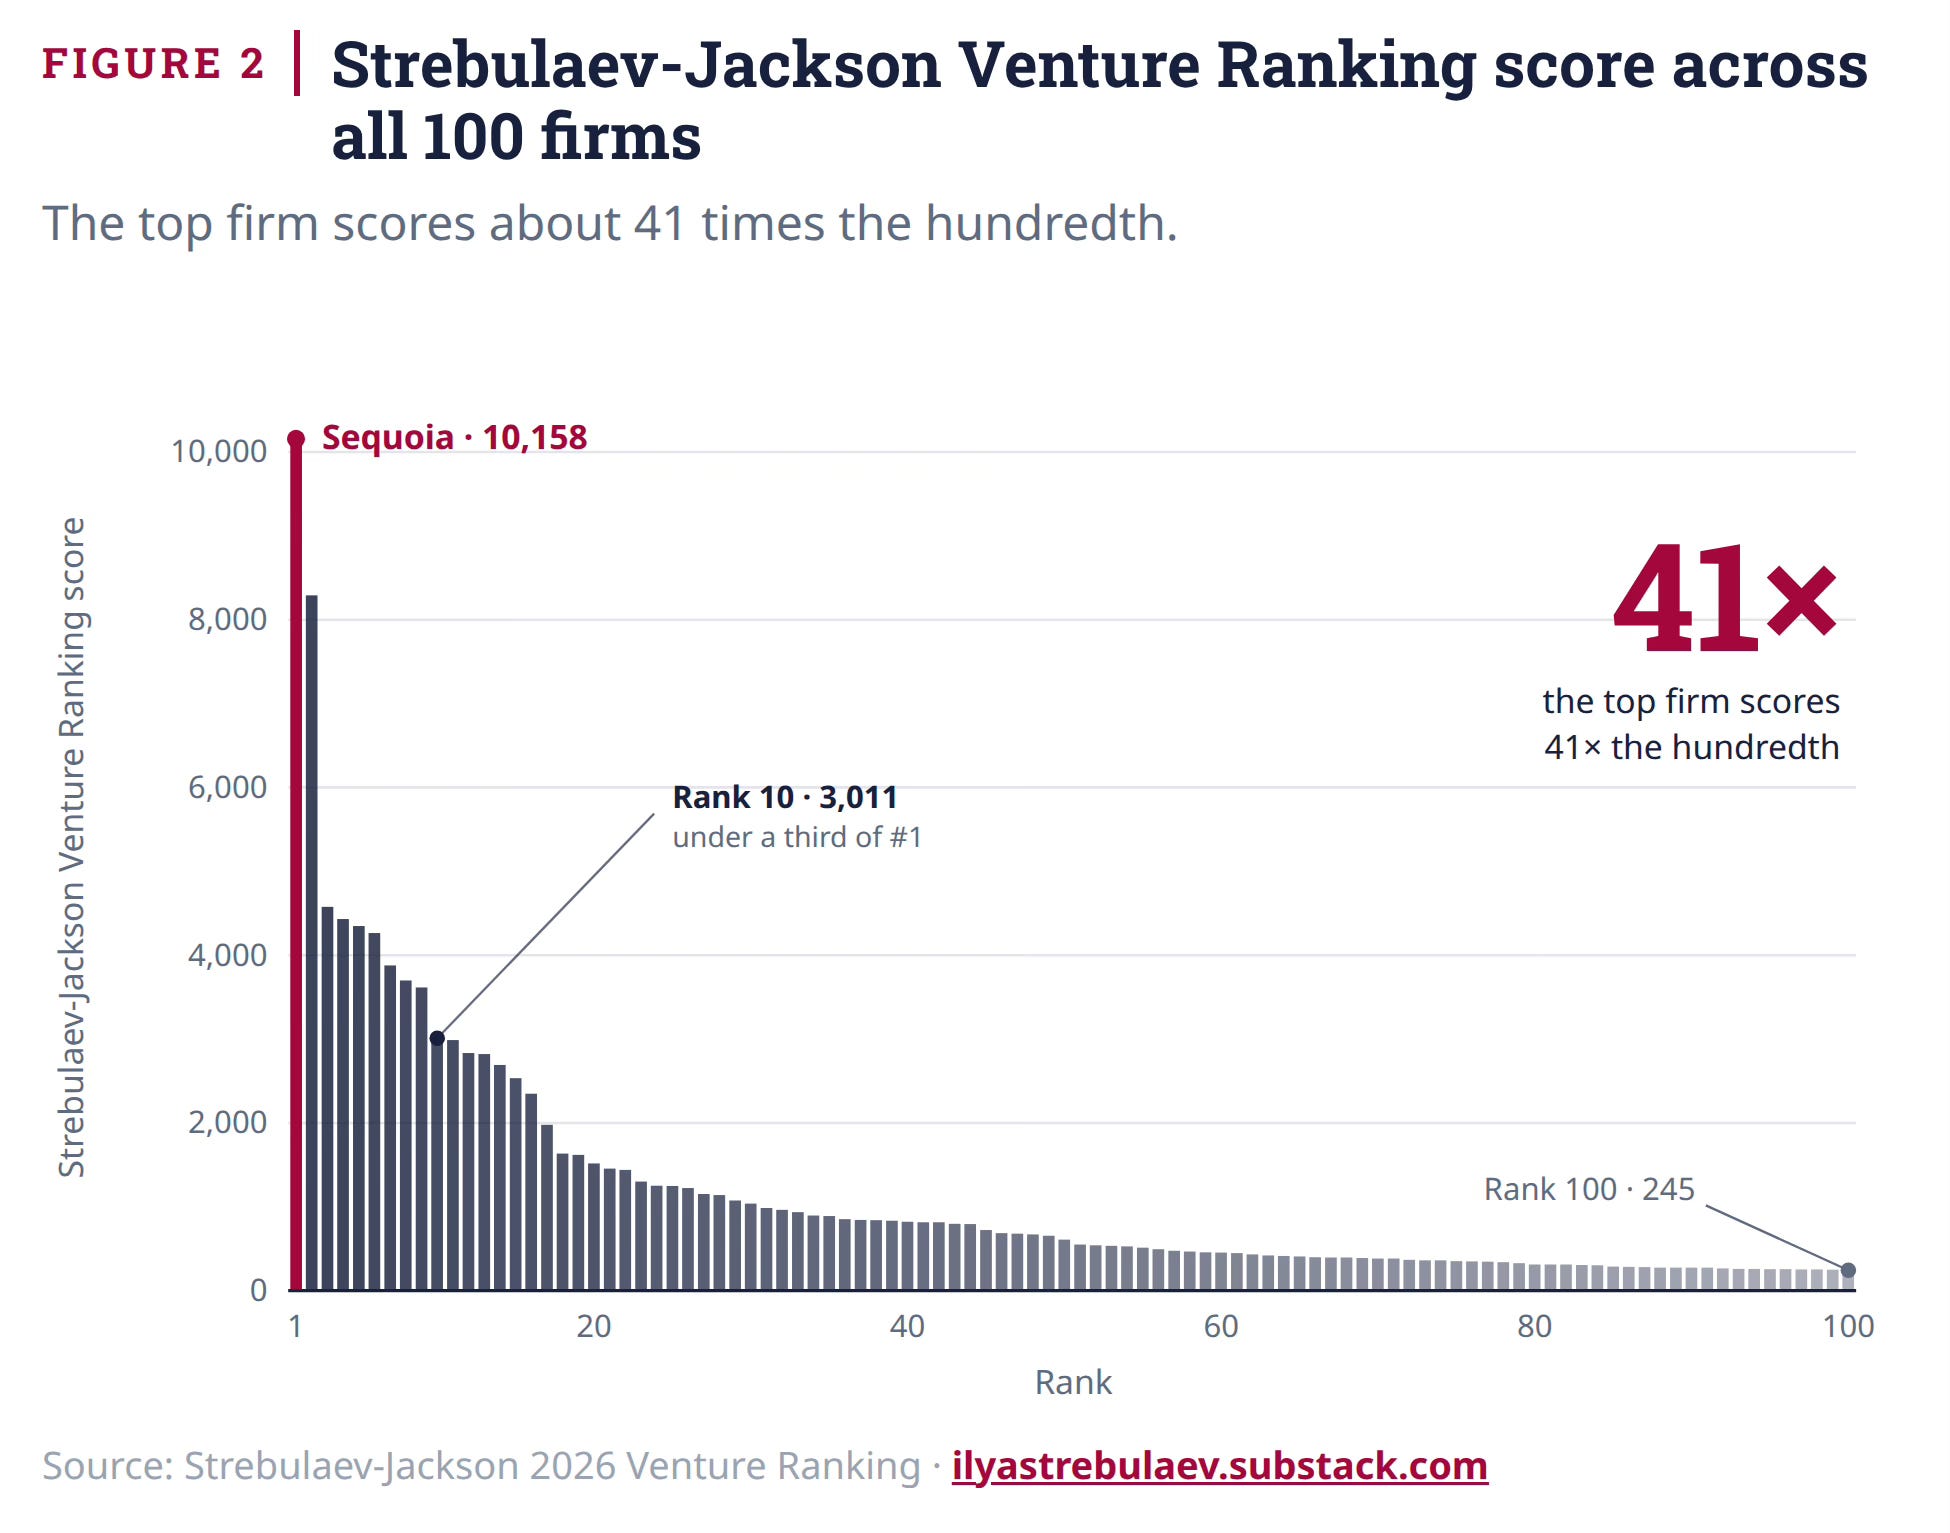
What stands out immediately is how steep the curve is. By rank 10 the score has fallen to roughly 3,000 — less than a third of Sequoia’s. By rank 100 it is 245. The top firm scores about 41 times the hundredth. Venture’s power law, so often described at the level of individual deals, applies just as forcefully to firms.
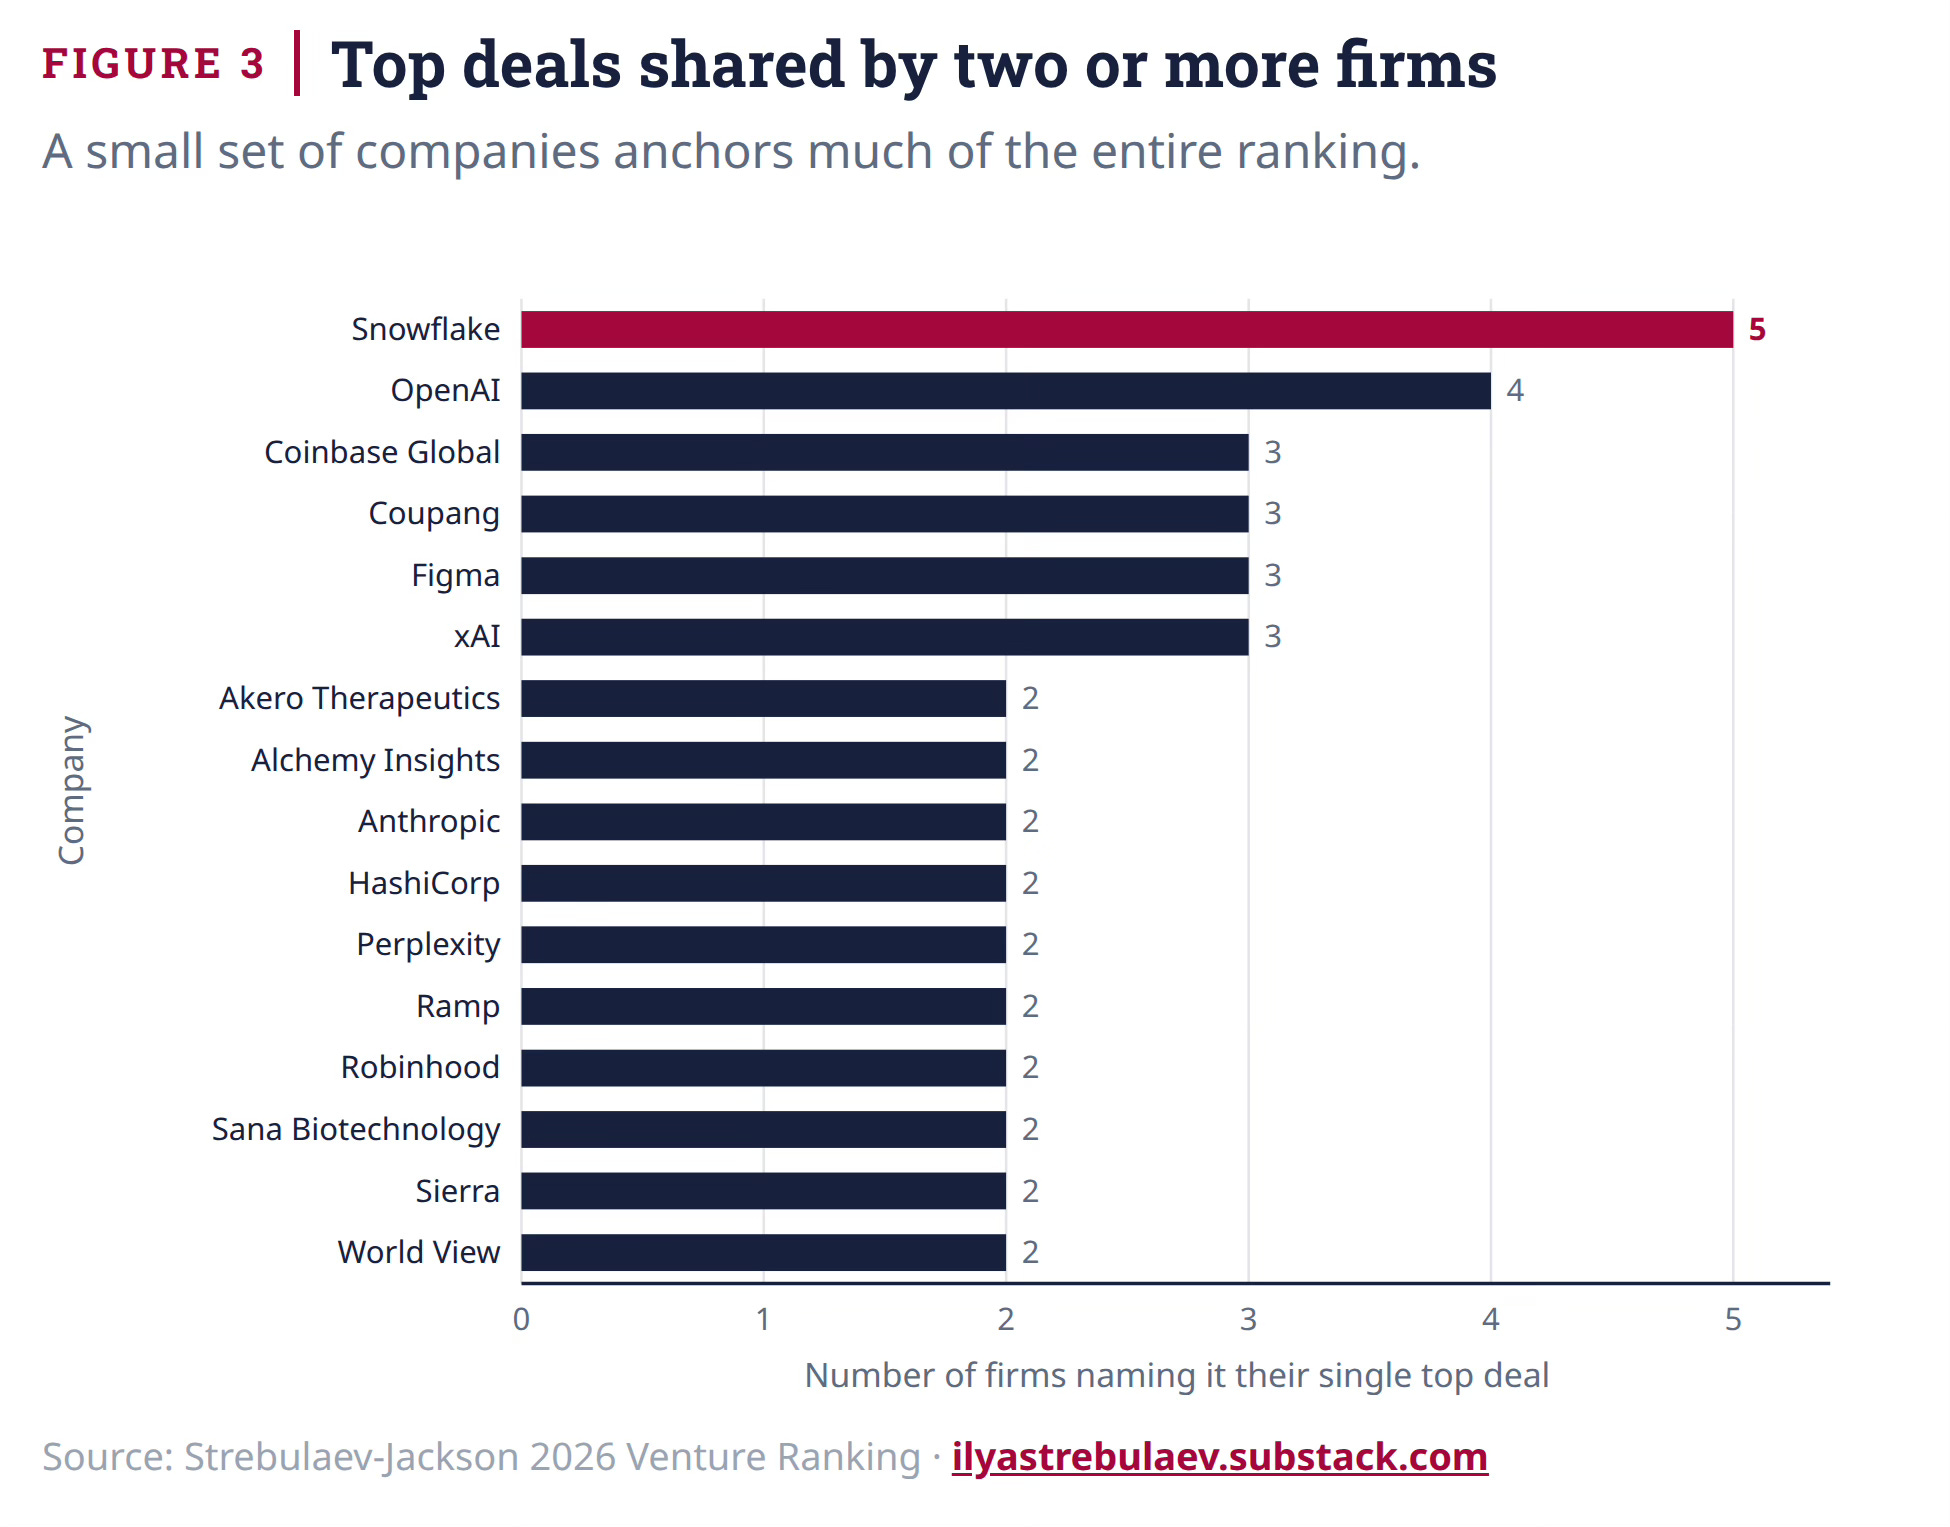
And the outcomes that drive these scores are remarkably concentrated. Across all 100 firms, there are only 74 distinct “top deal” companies — the single highest-scoring investment for many firms is the same handful of names. Snowflake is the top deal for five different firms; OpenAI for four; Figma, Coinbase, Coupang, and xAI for three each. A small set of companies anchors much of the entire ranking. This is precisely why identifying the right investors matters so much, and why the absence of a credible, transparent ranking has been such a gap. The individual rankings that will be released soon will show where that credit falls at the person level.
This is not just a unicorn-counting contest
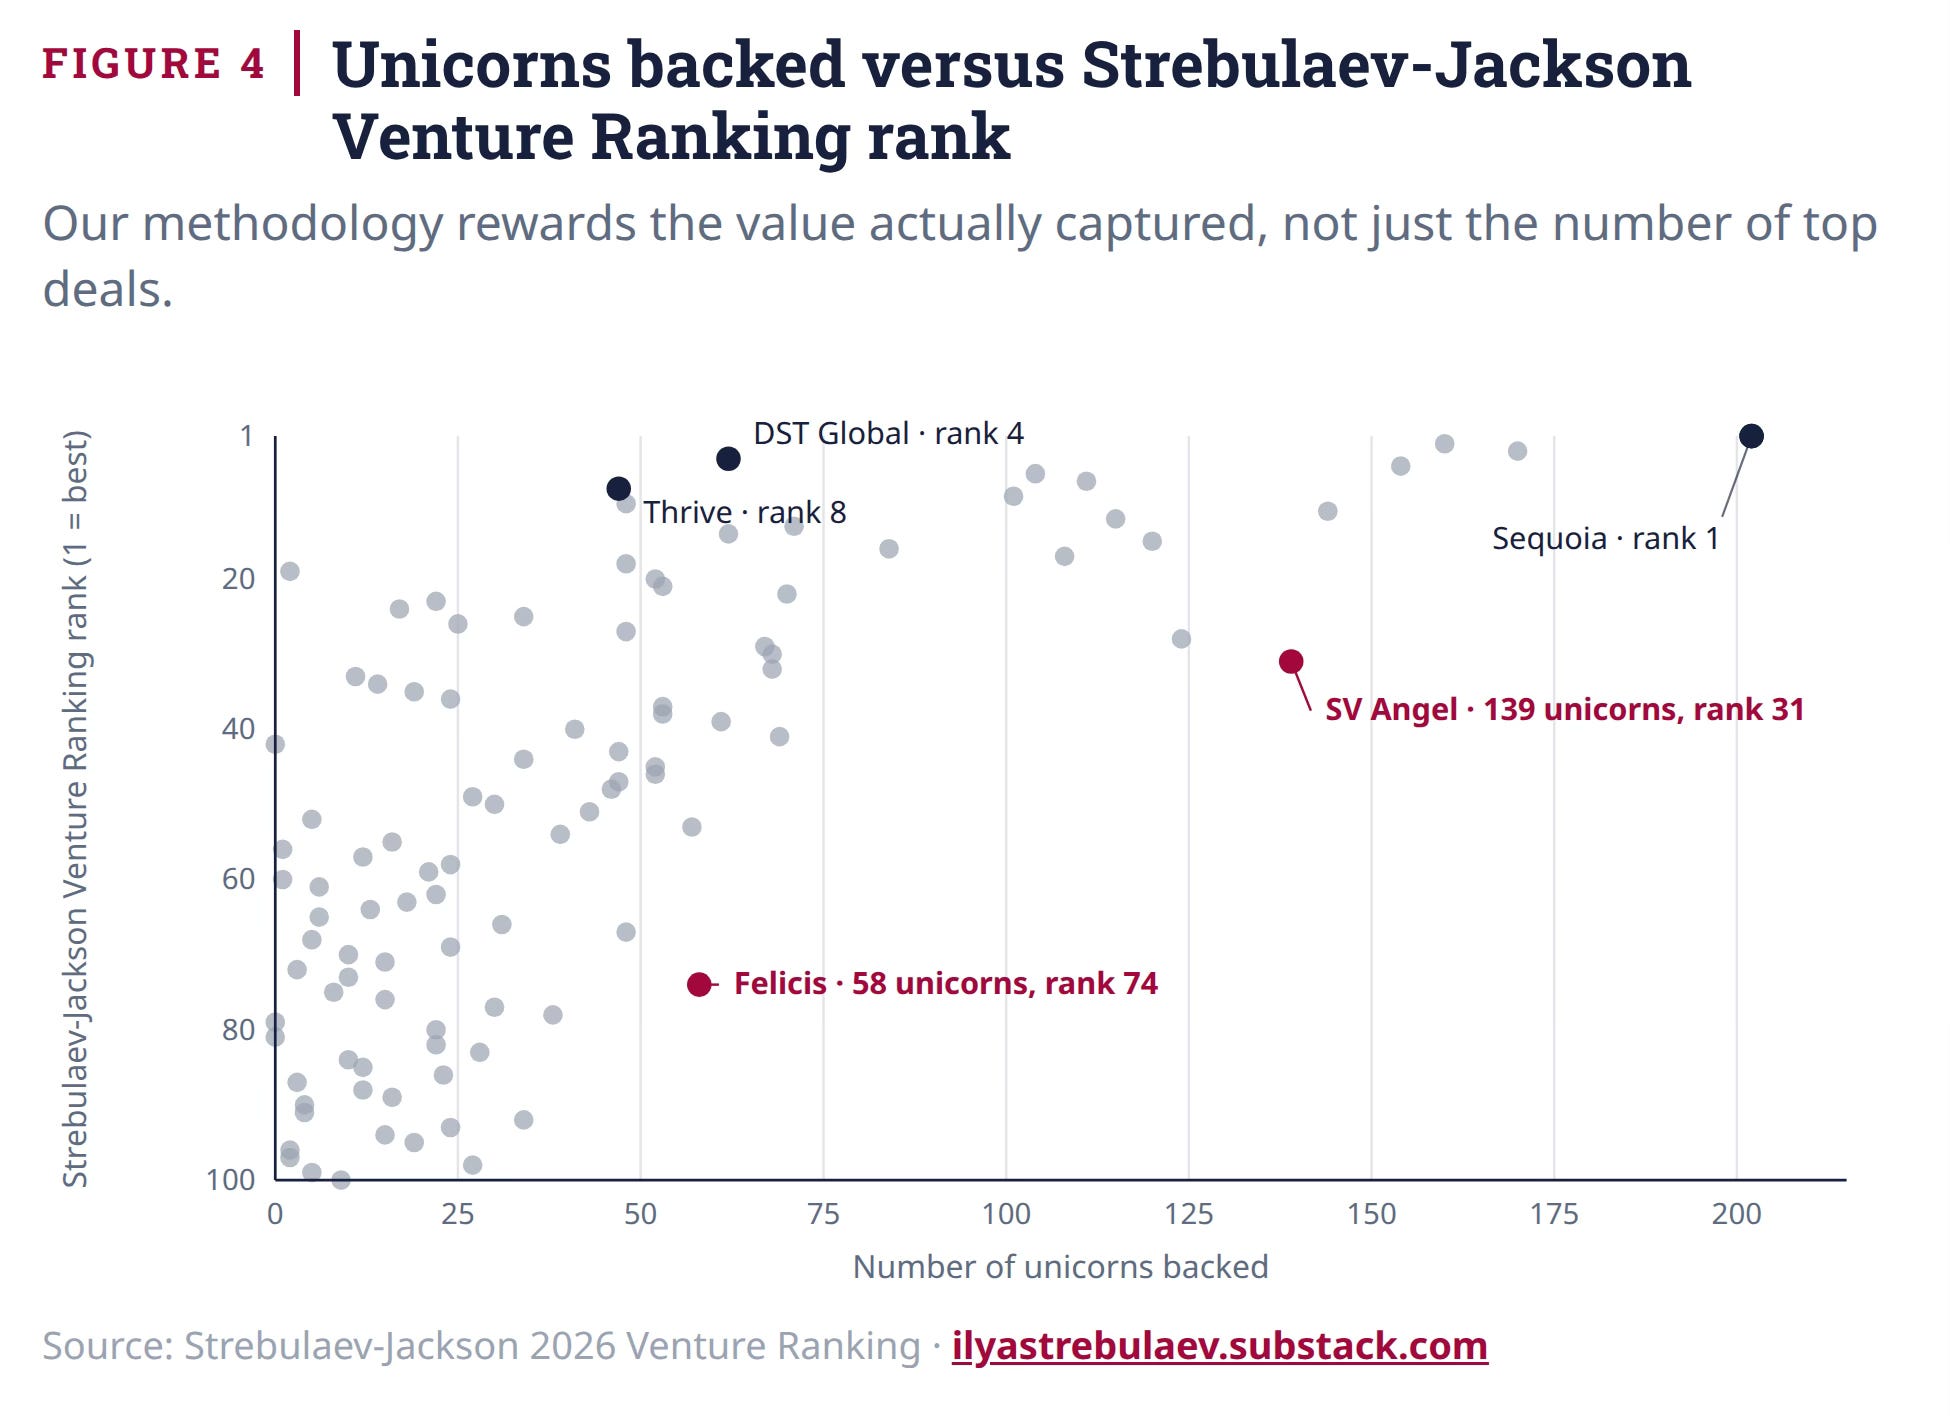
The ranking is not a tally of how many unicorns a firm has invested in (I produce quarterly rankings of investors by US and global unicorns). For example, SV Angel has backed roughly 139 unicorns, yet ranks 31st. Insight Partners has invested in about 124 and ranks 28th. Felicis has some 58 unicorns to its name and sits at 74th. Meanwhile DST Global invested in 62 unicorns yet ranks 4th, and Thrive is 8th with 47 unicorns.
How can a firm with a fraction of the unicorn count rank far higher? Our methodology rewards the value actually captured, not just the number of top deals. A firm that wrote a tiny, heavily diluted check into a company that later became a unicorn gets less credit for it — the dilution adjustment shrinks the stake, the net-profit adjustment subtracts the cost, and a small early position in a crowded cap table can be worth much less by exit. A firm that took a large, concentrated, board-level position in a smaller number of winners gets a great deal of credit. Expressed as points per unicorn, the spread is large: from around six for the highest-volume names to more than eighty for the most concentrated.
Old guard, new guard
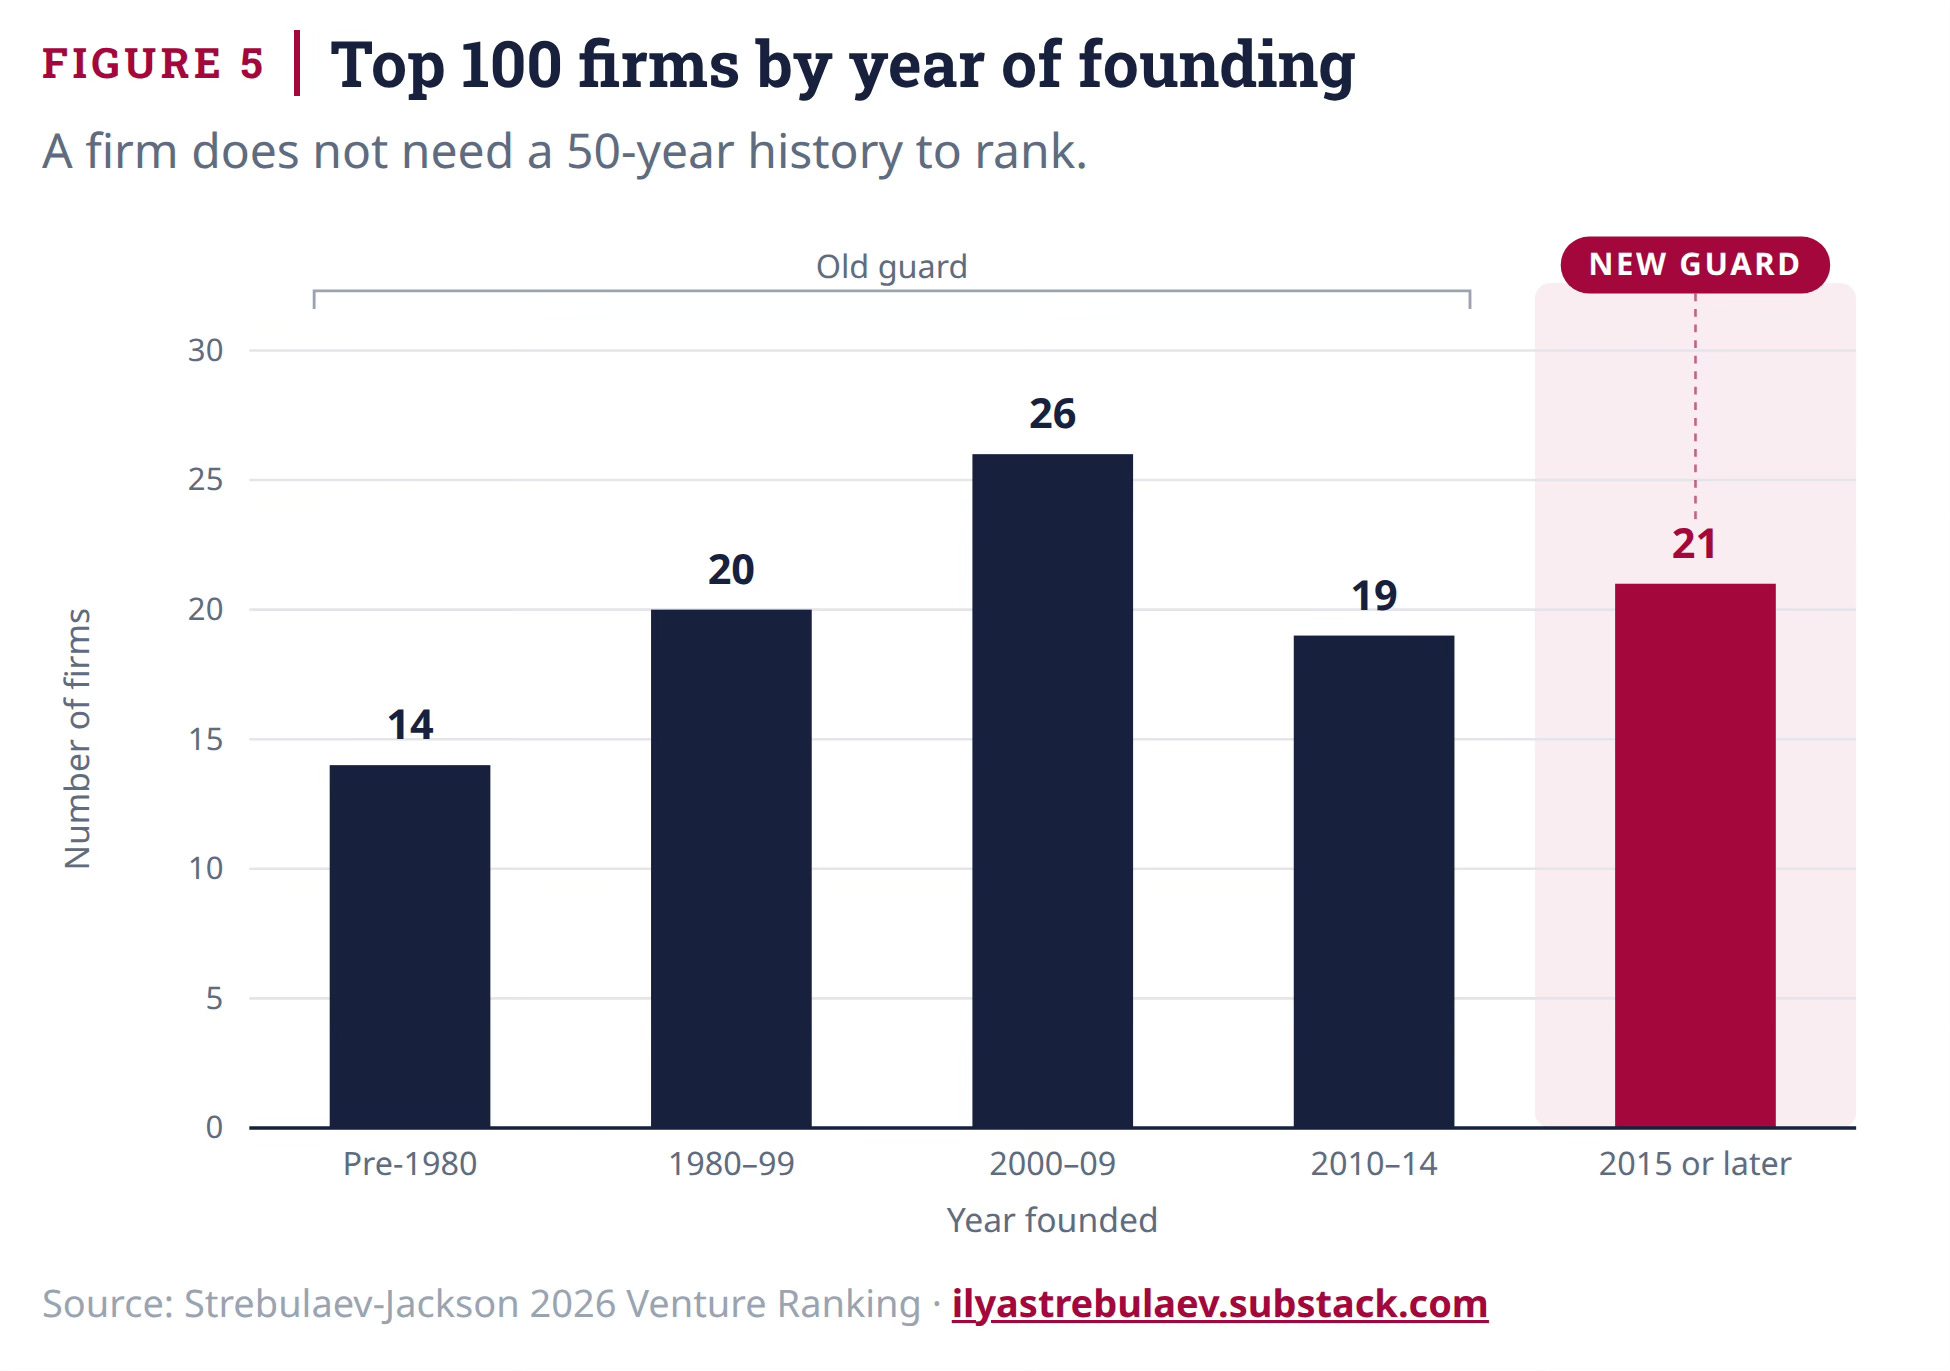
One of the more striking features of the list is its generational range. The oldest firm in the top 100, Bessemer, traces its venture capital roots to the 1970s; the youngest, Inflection Ventures, was founded in 2022. Eight of the top 20 firms predate 2000, a testament to how durable a genuine venture franchise can be. Sequoia (1972), Kleiner Perkins (1972), NEA (1977), and Accel (1983) all remain near the top half a century on.
Yet the decay factor ensures the list includes timely accounting of net profits. Twenty-one of the 100 firms were founded in 2015 or later, and several have rocketed up on the strength of a single recent, fast-appreciating bet. Parkway Venture Capital (founded 2019) sits at 19 on the back of Figure AI, and Bedrock (2018) made the list largely on its early OpenAI position. A firm does not need a 50-year history to rank.
AI is already rewriting the top of the table
The clearest signal of “right now” is artificial intelligence. For 23 of the 100 firms, the single highest-scoring investment for our inaugural firm rankings is a frontier-AI or AI-infrastructure company — OpenAI, Anthropic, xAI, Databricks, Scale AI, Mistral, Perplexity, CoreWeave, and others. That is nearly a quarter of the entire list, anchored to a wave of companies most of which did not exist, or were tiny, five years ago.
The decay factor ensures that the AI boom is already reshaping the ranking in real time. A handful of firms that placed early, concentrated bets on the leading AI companies — Thrive on OpenAI, Menlo on Anthropic, Lightspeed on Mistral — are being rewarded immediately rather than years after the fact.
Geography: still a Bay Area story
For all the talk of venture decentralizing, the top of the industry remains tightly clustered. Sixty-two of the top 100 firms are headquartered in California, the great majority in a narrow corridor from San Francisco down through Menlo Park and Palo Alto. New York is a distant second with 19 firms, concentrated in growth and crossover investing; Massachusetts and Texas follow with six each, with Boston and Cambridge anchoring a recognizable biotech-venture cluster.
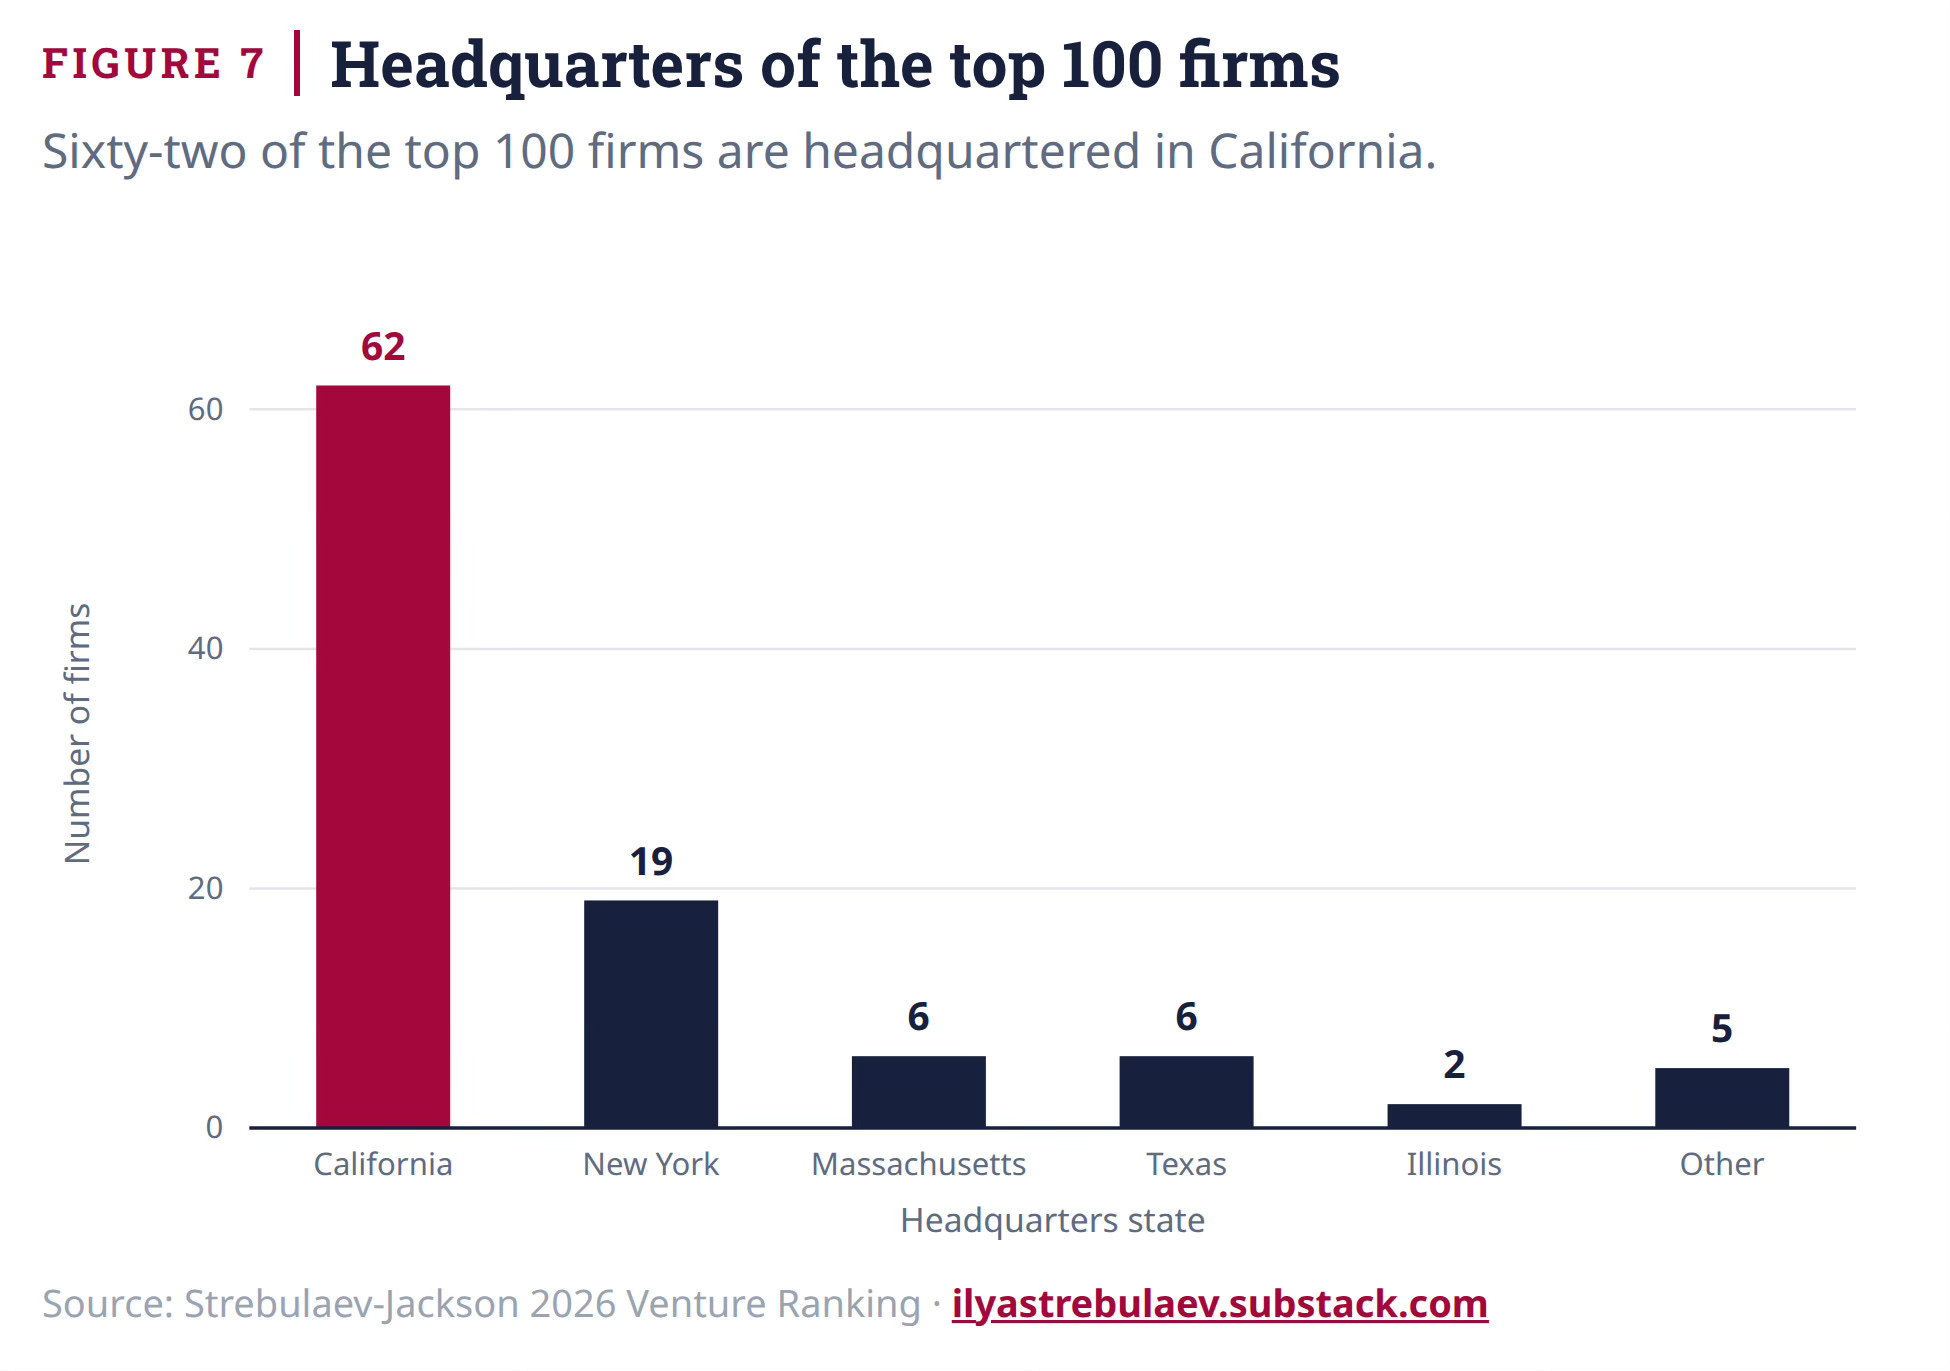
Whatever geographic broadening has happened at the seed and angel level, the institutional core of US venture has not left its historical home.
Specialists hold their own
The ranking is not purely a generalist-megafund affair. A distinct cluster of life-sciences specialists earns its place on concentrated, capital-efficient biotech bets: OrbiMed (27), Atlas Venture (38), ARCH (49), Versant (61), and Sofinnova (75) all rank on the strength of therapeutics and medical outcomes rather than software. A set of crypto-native firms — Paradigm (34), Pantera (76), Multicoin (84), Polychain (94) — ranks on a completely different opportunity set again. The methodology does not privilege any sector; it simply measures value created, net of cost and decay, wherever it occurs. That a focused biotech firm can sit alongside a multistage giant is a feature, not a bug.
For founders and capital allocators interested in a specific space: I will be releasing industry-focused VC firm rankings soon.
One yardstick, many playbooks
Because the ranking applies a single standard, it lets us compare different investment models. A number of VC firms belong to the crossover and hedge-fund-style cohort — Tiger Global (5), DST Global (4), Coatue (29), Altimeter (24), Dragoneer (23), Greenoaks (44). These firms tend to have large minority stakes and few or no board seats, in contrast to the deeply involved, board-heavy models of firms such as Sequoia and Benchmark.
The individual ranking lands next — and it breaks with conventional wisdom.
Half of our top 100 VC firms have no partner in the individual top 100. We will be releasing the 2026 Individual VC ranking soon. Our main rankings are free to everyone. Paid and founding members get early access, additional rankings, plus extra detail on firms and individuals.
The full 2026 ranking — all 100 firms
Below is the complete ranking: rank, firm, Venture Ranking score and top deal.
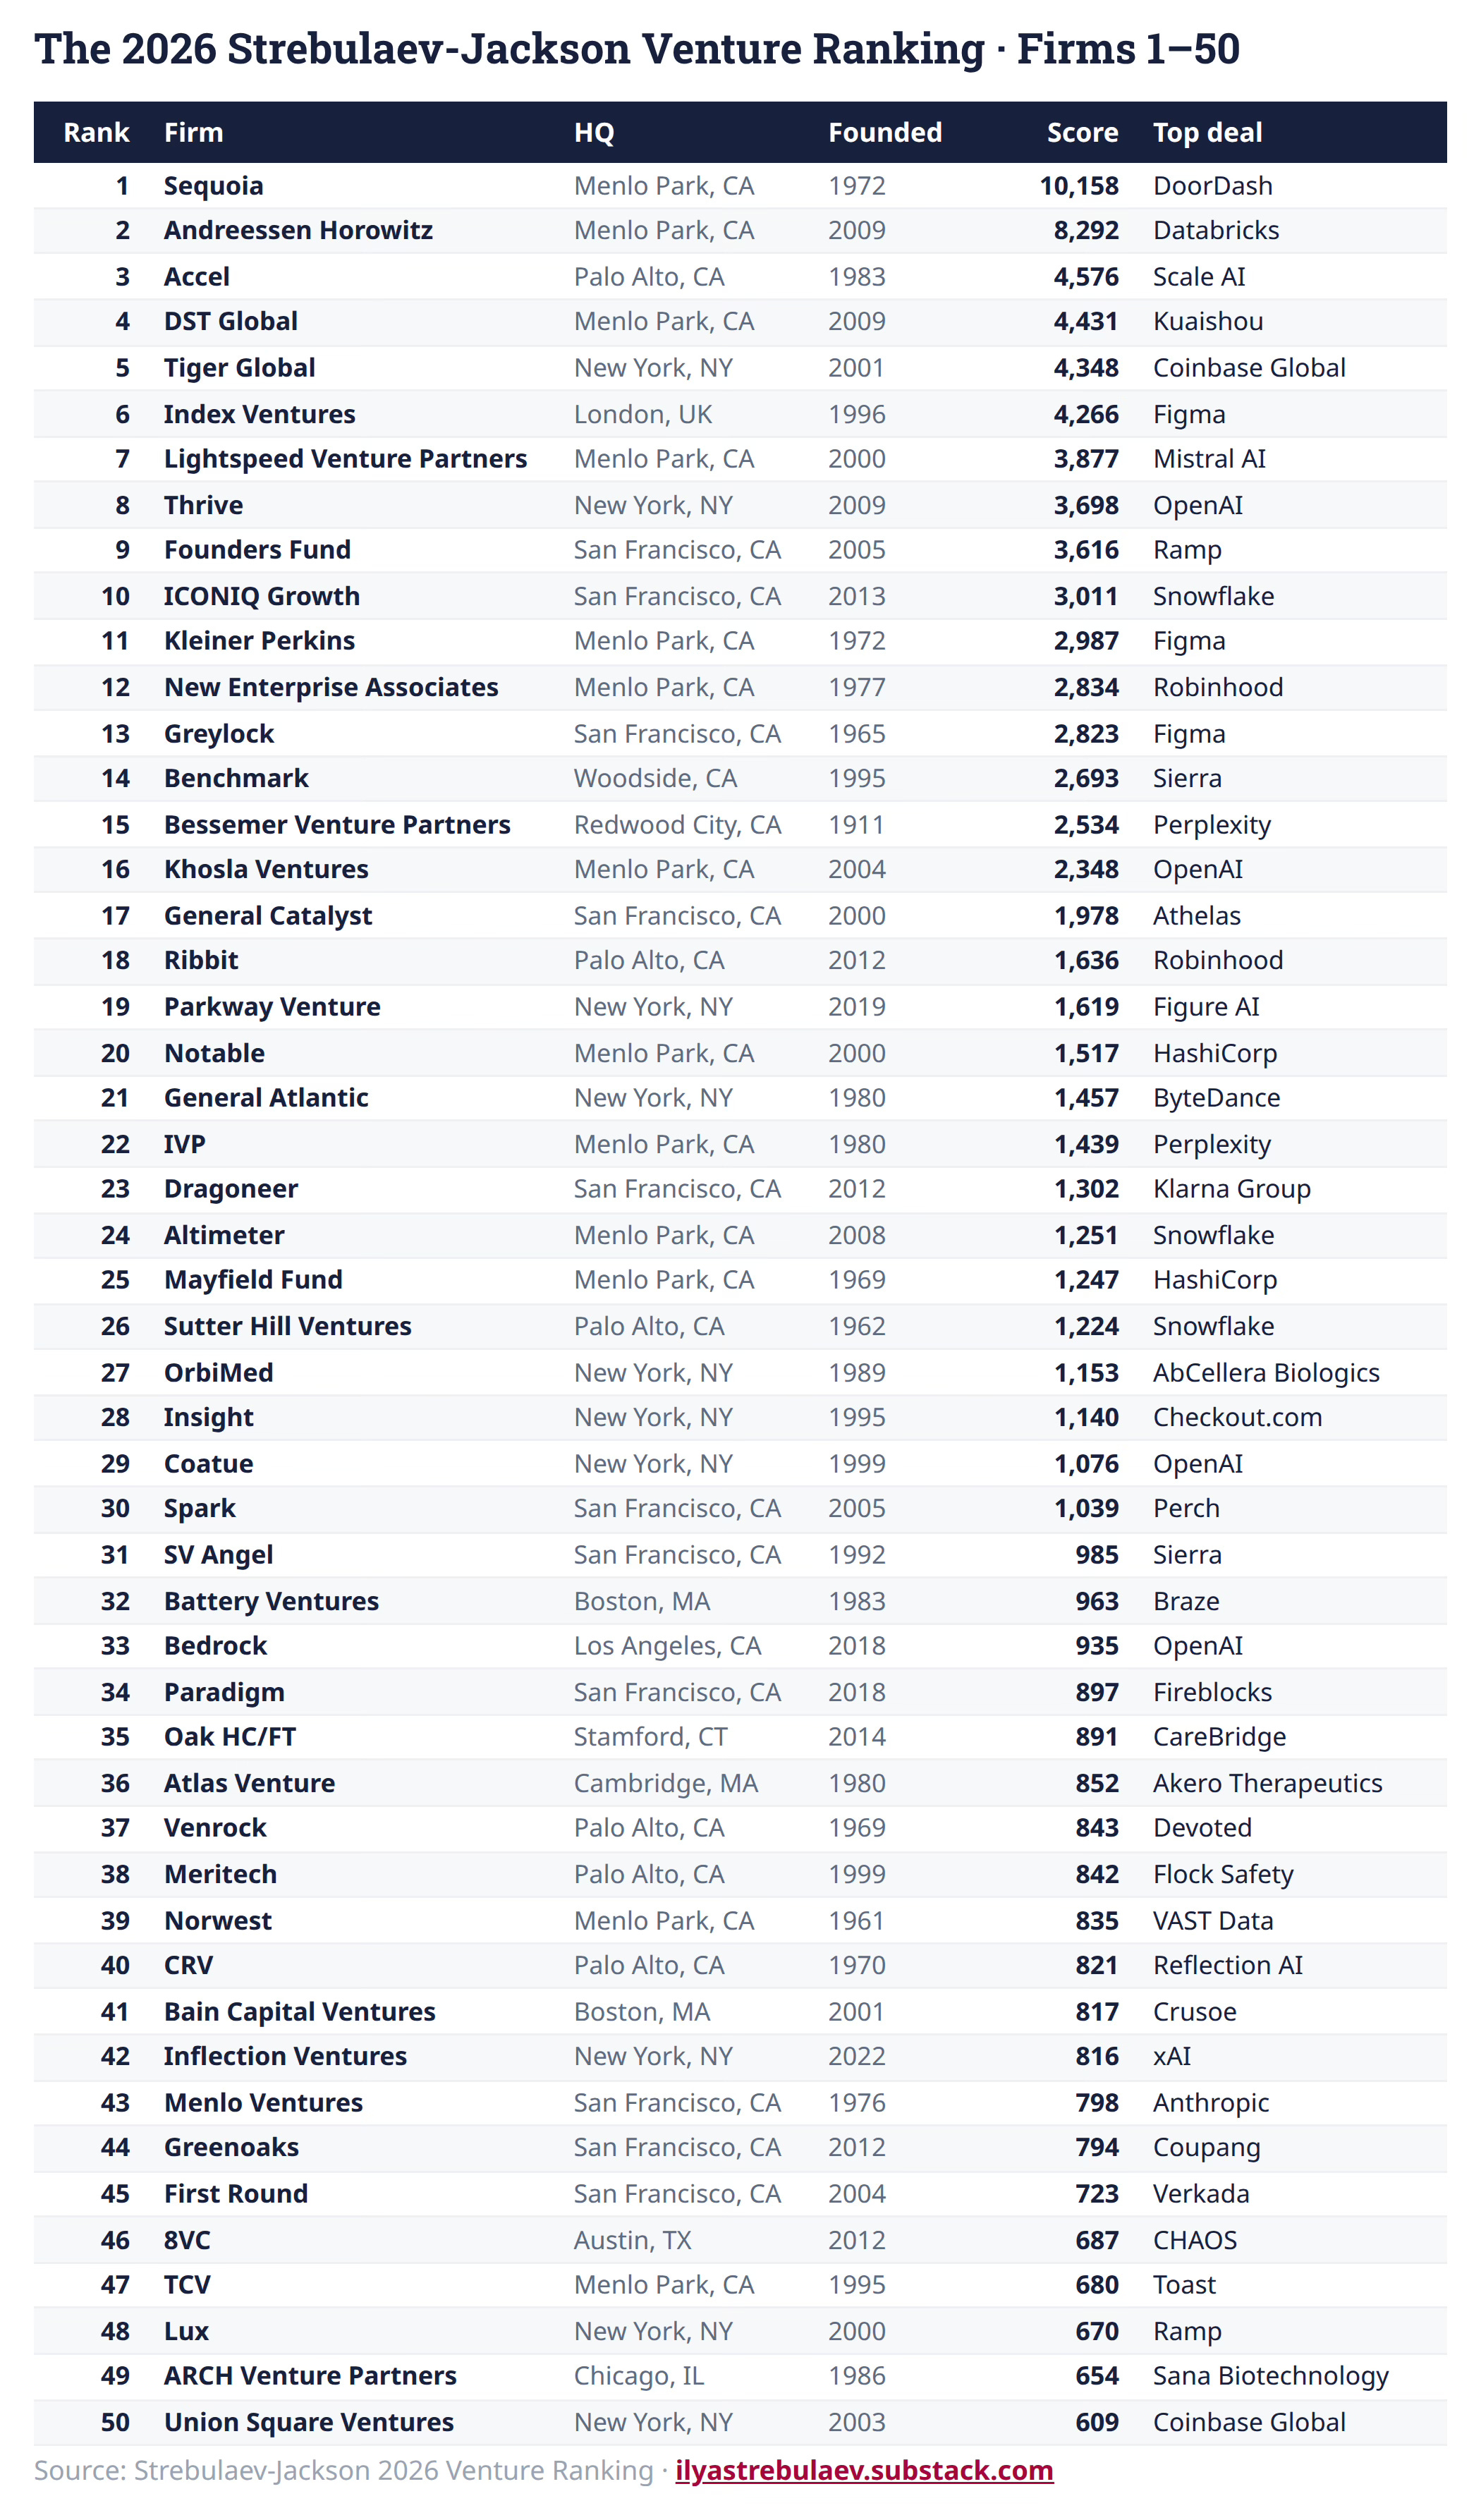
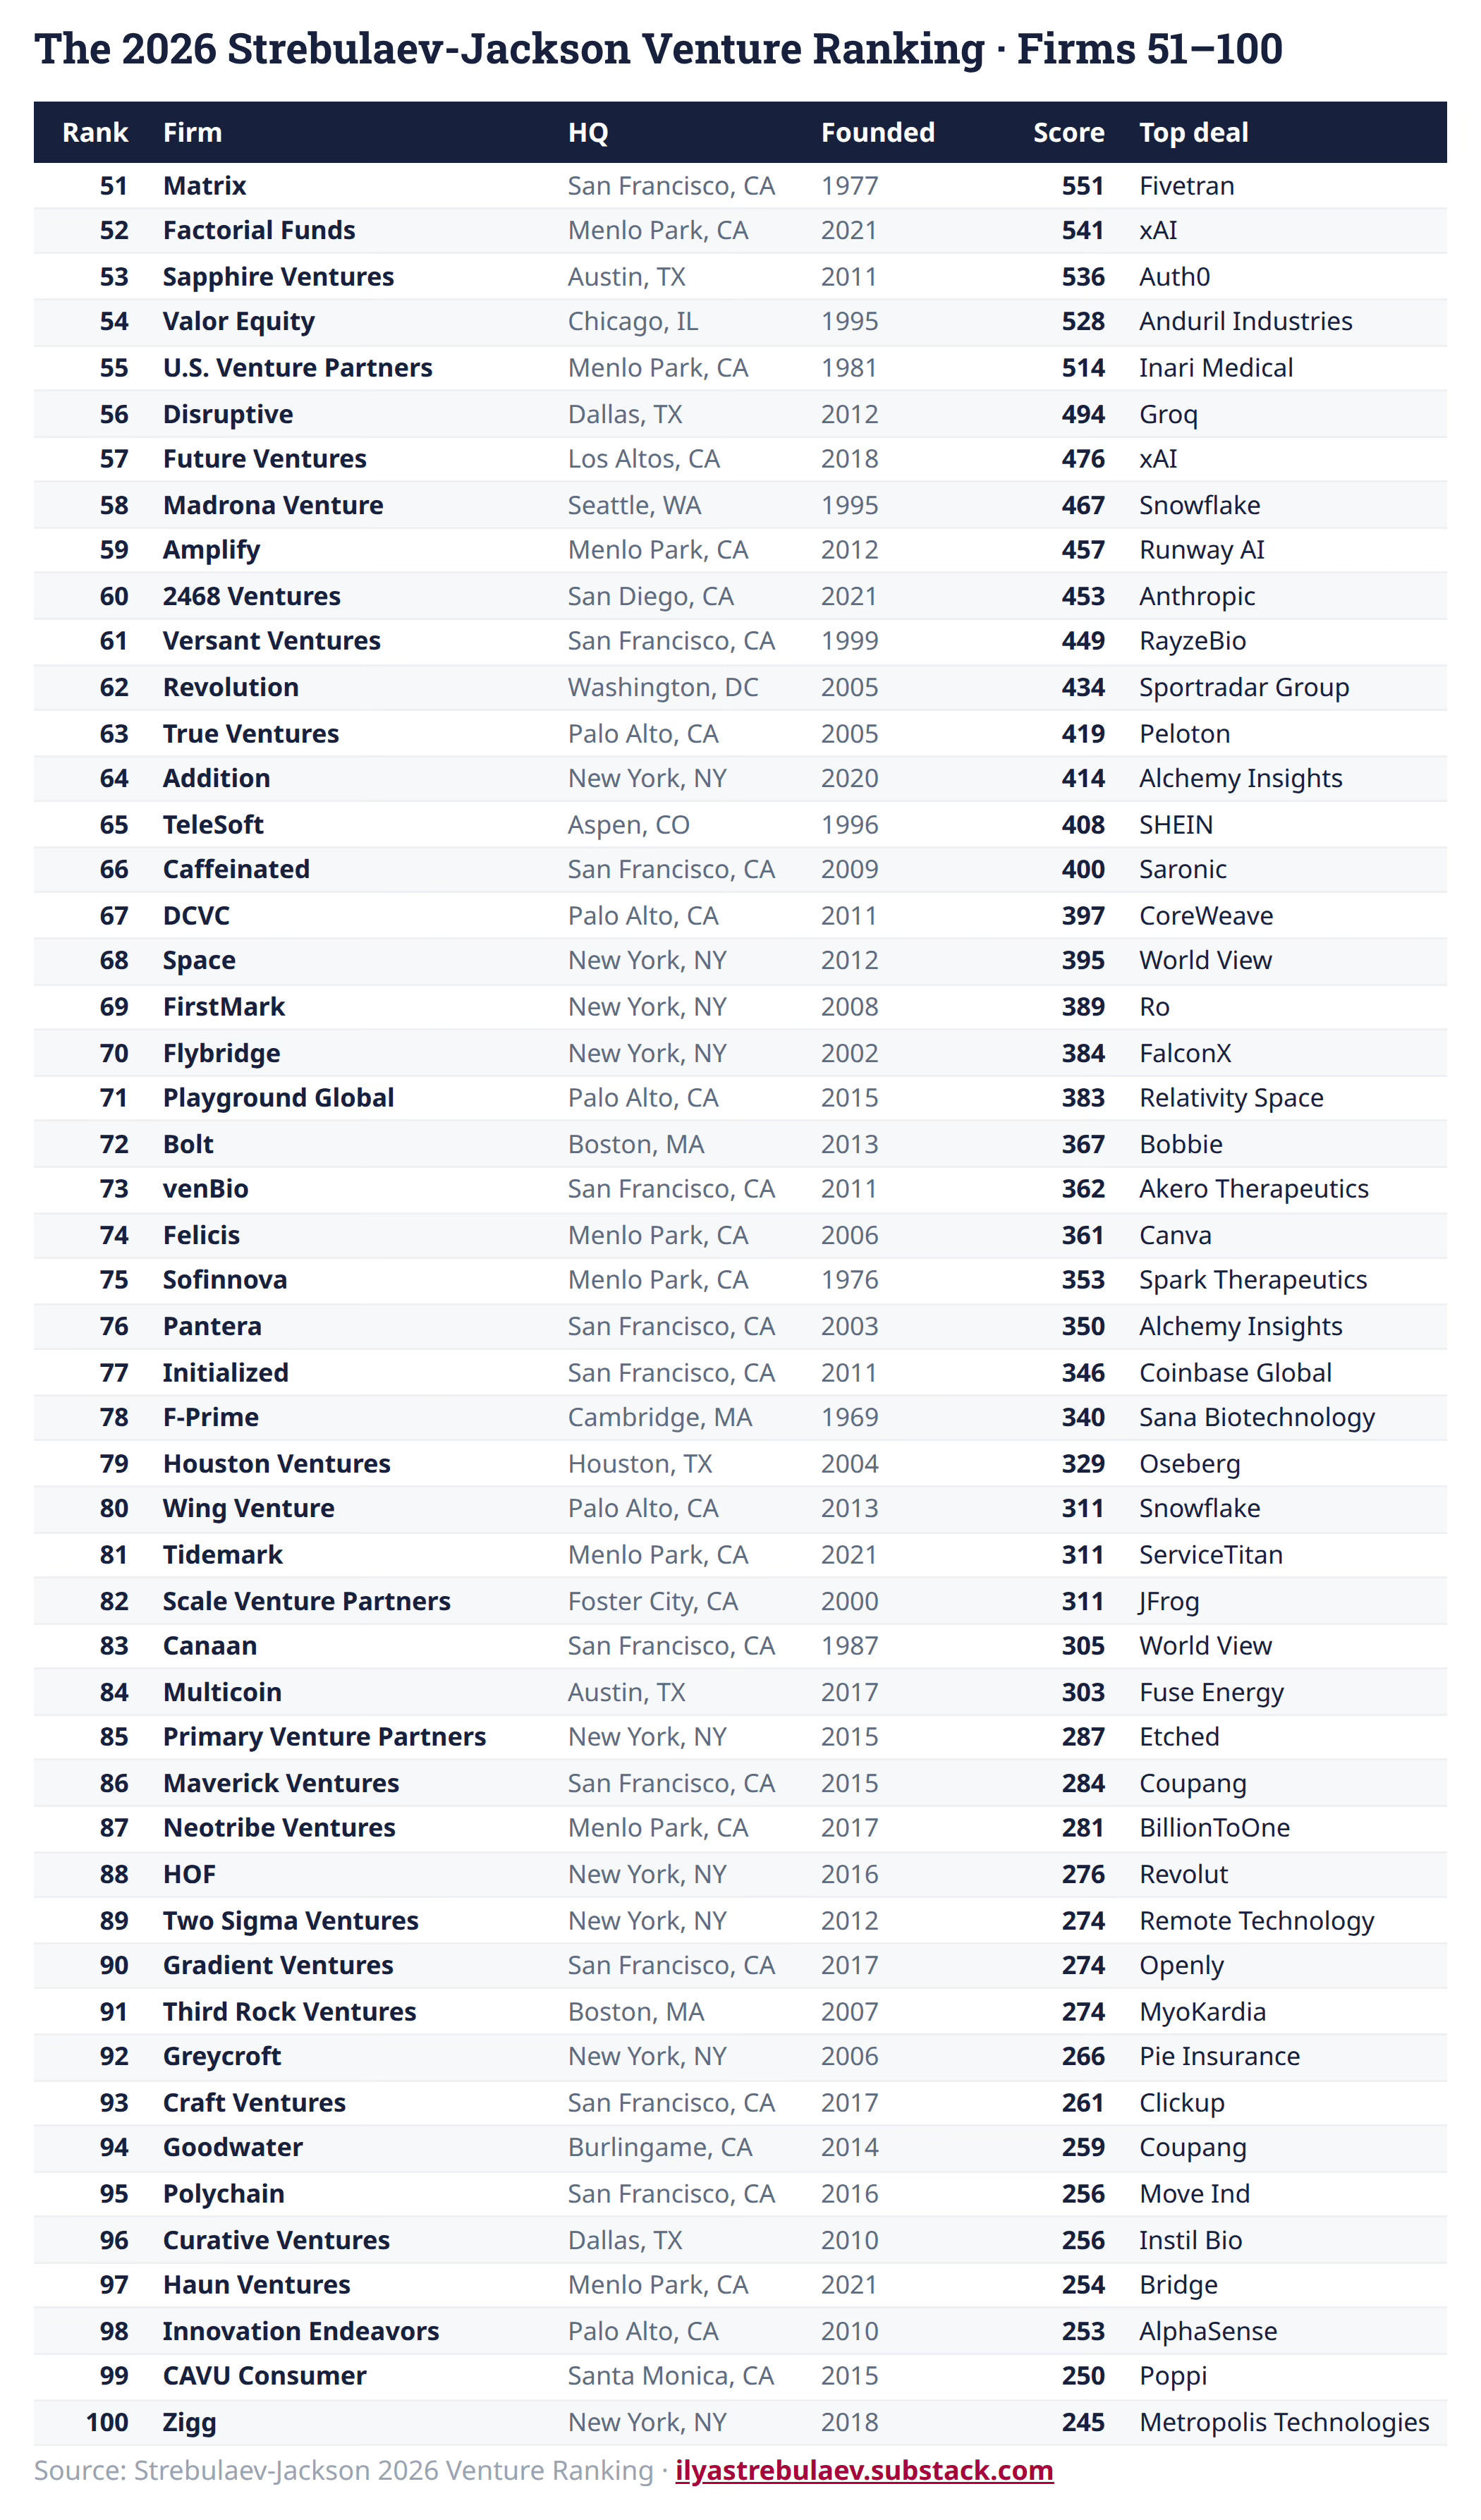
The “top deal” is the single highest-scoring investment for that firm under our methodology — not necessarily its most famous or highest-valued holding.
2026 Ranking of VC Firms — please log in using your Substack email to see the spreadsheet with additional information.
A PDF version of this article, including the full 2026 Ranking of the Top 100 VC Firms, can be downloaded here: White paper
An extended version of this ranking (101-200) is available to paid subscribers:
